
- What does the company do?
- Why Some Investors Are Bullish
- What Bears Are Worried About
- Why the Quants like this stock
- My View
What does the company do?
Micron Technology develops and manufactures memory and storage semiconductor products worldwide. Its portfolio includes DRAM, NAND, high-bandwidth memory (HBM), solid-state drives, and other memory solutions used in data centers, PCs, smartphones, networking, automotive, and industrial applications. Micron sells its products under the Micron and Crucial brands and serves customers through direct sales, distributors, retailers, and other partners. Founded in 1978 and headquartered in Boise, Idaho, Micron is a major supplier of memory technology for the growing AI and data-center markets.
Why Some Investors Are Bullish
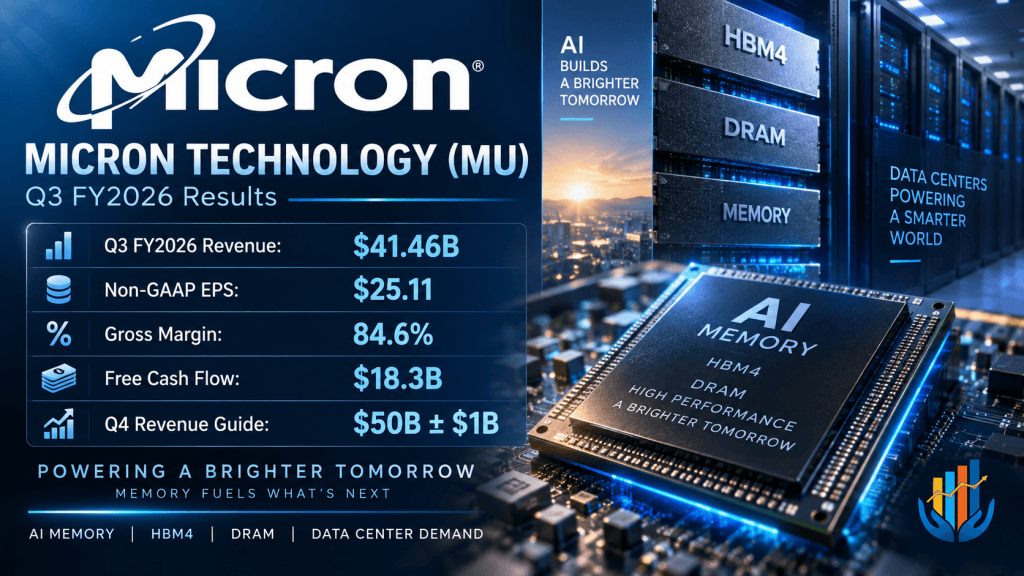
- Record Q3 results — Micron reported $41.46 billion in revenue, compared with $9.30 billion a year earlier. GAAP EPS was $24.67, while non-GAAP EPS reached a record $25.11. GAAP gross margin surged to 84.6%, versus 37.7% a year earlier.
- AI is driving exceptional demand — Micron said HBM4 had entered high-volume shipments for its lead customer’s platform, while qualification samples had been shipped to additional customers. The company also highlighted strong demand across its data-center memory and storage businesses as AI workloads require substantially more memory.
- Q4 guidance points to another record quarter — Micron expects fiscal Q4 revenue of approximately $50 billion ± $1 billion, with non-GAAP EPS of $31.00 ± $1.00 and gross margin of approximately 86%. If achieved, that would represent another substantial sequential increase from Q3.
- Cash generation and the balance sheet have strengthened significantly — Micron generated a record $25.4 billion of operating cash flow and $18.3 billion of free cash flow in Q3. It ended the quarter with $30.2 billion of cash and investments, $5.7 billion of debt and $24.4 billion of net cash.
- Multi-year customer agreements could improve visibility — Micron said it has entered into strategic customer agreements that it expects to enhance the durability and predictability of its financial performance. At the same time, the company is investing heavily in additional technology and manufacturing capacity to meet expected demand.
What Bears Are Worried About
- Expectations are extremely high heading into September 30 — After an extraordinary increase in revenue, earnings and margins, investors are likely to focus heavily on whether Micron can meet or exceed its already aggressive Q4 outlook. Any indication that demand, pricing or margins are beginning to moderate could have a significant effect on the shares.
- Memory remains a cyclical business — Micron’s current 84%+ gross margins are extraordinary compared with its historical results. Memory pricing and profitability can change rapidly when supply and demand move out of balance, so today’s exceptional margins should not automatically be viewed as a permanent baseline.
- Capacity expansion carries execution risk — Micron is investing at record levels to expand technology and manufacturing capacity while trying to keep pace with AI-related demand. If industry demand ultimately grows more slowly than expected, the resulting increase in supply could put pressure on pricing and margins. Management itself has emphasized the need for substantial investment to address customer demand.
Why the Quants like this stock
P/E Non-GAAP (FWD) A- 13.83
PEG Non-GAAP (FWD) A+ 0.08
Revenue Growth (FWD) A+ 113.85%
EPS FWD Long Term Growth (3-5Y CAGR) A+ 176.11%
ROE Growth (FWD) A+ 260.71%
Return on Common Equity (TTM) A+ 66.64%
1Y Price Performance A+ 501.46%
FY1 Up Revisions (last 90 days) 32 Up and 1 Down
Latest Quarter’s Earnings
Announce Date 6/24/2026
EPS GAAP Actual $24.67 (Beat by $3.65)
EPS Normalized Actual $25.11 (Beat by $4.42)
Revenue Actual $41.46B
Revenue Surprise Beat by $5.64B
My View
Micron enters its September 30 earnings report with extraordinary momentum: record revenue, record cash generation, very high margins, strong AI-related demand and an exceptionally strong balance sheet. The bigger question for investors is no longer simply whether Micron is benefiting from the AI memory boom, but how long the current combination of pricing, demand and margins can remain at these unusually high levels.
All content on this site is for informational purposes only and does not constitute financial advice. Consult relevant financial professionals in your country of residence to get personalized advice before you make any trading or investing decisions. This post was written with the assistance of artificial intelligence. The original ideas and final review are human-generated. Disclaimer
Copyright 2023-2026 SwingTrader.Trading. All Rights Reserved.
 Position Trader
