
- Selection for this week
- Some Pros about the stock
- Some Cons about the stock
- Why the Quants like this stock
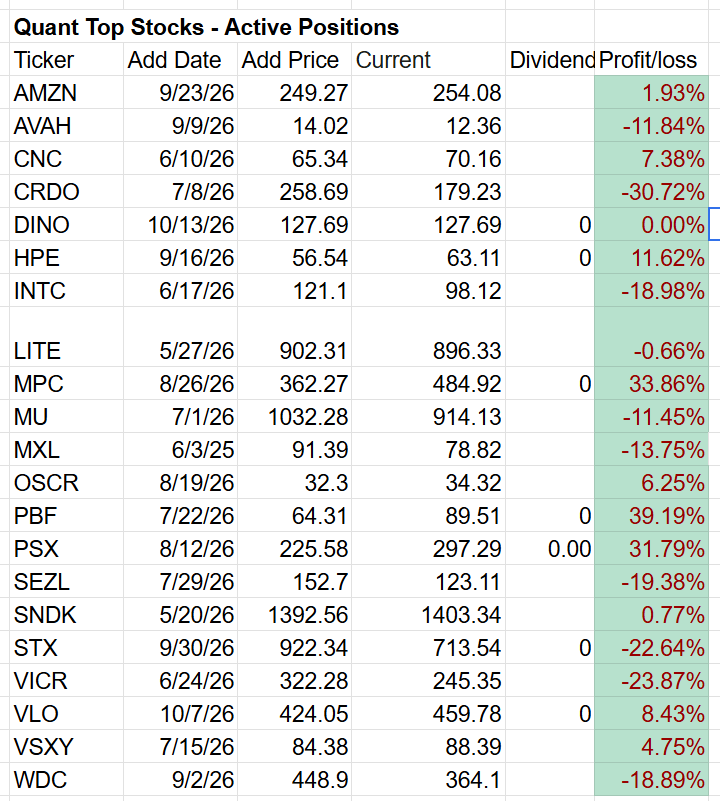
- Active Positions
- Quick Links
The momentum stocks in the portfolio as a group dropped since last Thursday following the Risk Off trend in the market this week.
NESR (National Energy Services Reunited) becomes the first stock removed from the quant Top Stocks Portfolio. It was removed after its Momentum and EPS Revision ranking fell below the acceptable levels. A good portion of their business comes from Saudi Arabia and this affected the outlook for the stock among analysts in a negative way.
Add: DINO (HF Sinclair Corporation)
Remove: NESR (National Energy Services Reunited)
What does the company do?
HF Sinclair Corporation (NYSE: DINO) is an independent energy company headquartered in Dallas, Texas. Founded in 1947, it operates across five segments: Refining, Renewables, Marketing, Lubricants & Specialties, and Midstream. The company operates refineries across the western and central United States, producing gasoline, diesel, jet fuel, renewable diesel, asphalt, specialty chemicals, and lubricants. HF Sinclair also markets fuel through approximately 1,700 branded stations and licenses the Sinclair brand to additional locations. Its midstream operations provide crude oil and refined-product transportation, storage, and terminal services, while its products are sold domestically and internationally.
Why Some Investors Are Bullish
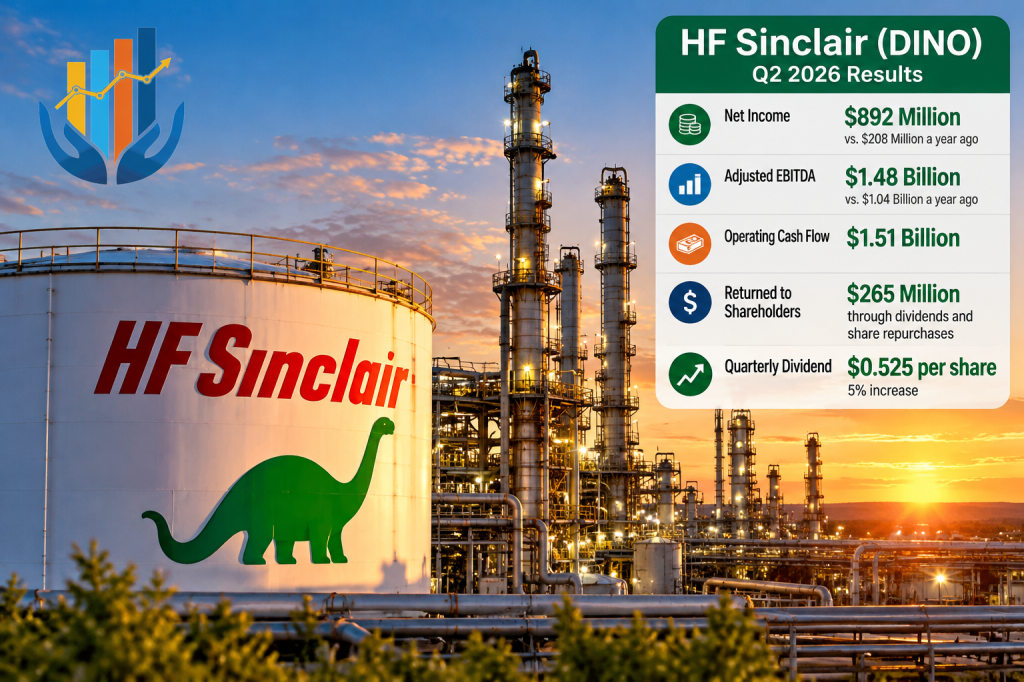
- Strong earnings growth. Second-quarter 2026 net income rose to $892 million from $208 million a year earlier. Adjusted EBITDA increased to $1.48 billion, supported by stronger refining margins and operating performance.
- Attractive valuation. DINO’s valuation remains relatively modest based on recent earnings. However, refining profits are cyclical, so investors should consider normalized earnings rather than assuming current profitability will persist.
- Growing dividend. In July 2026, HF Sinclair raised its quarterly dividend by 5% to $0.525 per share. The annualized payout is $2.10 per share, although the current yield changes with the stock price.
- Strong cash generation and shareholder returns. The company generated $1.51 billion in operating cash flow during Q2 and returned $265 million to shareholders through dividends and share repurchases. It ended June with $2.26 billion in cash and $2.77 billion in consolidated debt.
- Multiple business segments. Beyond refining, HF Sinclair operates in marketing, renewables, lubricants and midstream services. These businesses provide additional earnings sources and may help diversify its exposure to refining margins.
What Bears Are Worried About
- Cyclical earnings and commodity risk. Profitability can change significantly with refining margins, crude oil costs, fuel demand and seasonal conditions. A decline in crack spreads could reduce earnings and cash flow even if refinery operations remain strong.
- Long-term energy transition risks. Electric vehicle adoption, changing fuel consumption, environmental regulations and the transition toward lower-carbon energy could pressure conventional fuel demand over time. Renewable fuels also face changing economics and policy incentives.
- Elevated expectations and business-transition risks. DINO’s share price has risen sharply, increasing the risk of a pullback if refining margins weaken or earnings disappoint. The company also announced plans to separate its Lubricants & Specialties business, creating potential execution and restructuring risks.
Why the Quants like this stock
P/E Non-GAAP (FWD) A- 7.03
ROE Growth (FWD) A+ 123.93%
Return on Common Equity (TTM) B+ 19.41%
3M Price Performance A+ 56.95%
FY1 Up Revisions (last 90 days) 14 Up 0 Down
Latest Quarter’s Earnings
Announce Date 7/28/2026
EPS GAAP Actual $4.93 (Beat by $0.45)
EPS Normalized Actual $5.31 (Beat by $0.82)
Revenue Actual $10.39B
Revenue Surprise Beat by $1.44B
My View
HF Sinclair offers exposure to strong refining profitability, substantial cash generation and a growing dividend. The primary risk is cyclicality: unusually strong refining earnings may not be sustainable. After the stock’s substantial advance, valuation should be assessed against normalized earnings and future refining conditions, not simply recent results.
Active Positions
Quick Links
- Live Scorecard
- Model Portfolio Quant Alpha’s II
- Click here for the Quant Alpha’s II details
- Model Portfolio Quant 30
- Click here for the Quant 30 details
- Model Portfolio Quant Dividend and Growth 25
- Model Portfolio Quant Top Stocks
- Click here for the Quant Top Stocks details
- Model Portfolio Quant Alpha’s – Legacy
- Click here for the Quant Alpha’s – Legacy details
- Position Trader educational blog posts
- Position Trader – blog post user guide
All content on this site is for informational purposes only and does not constitute financial advice. Consult relevant financial professionals in your country of residence to get personalized advice before you make any trading or investing decisions. This post was written with the assistance of artificial intelligence. The original ideas and final review are human-generated. Disclaimer
Copyright 2023-2026 SwingTrader.Trading. All Rights Reserved.

