
- Selection for this week
- Some Pros about the stock
- Some Cons about the stock
- Why the Quants like this stock
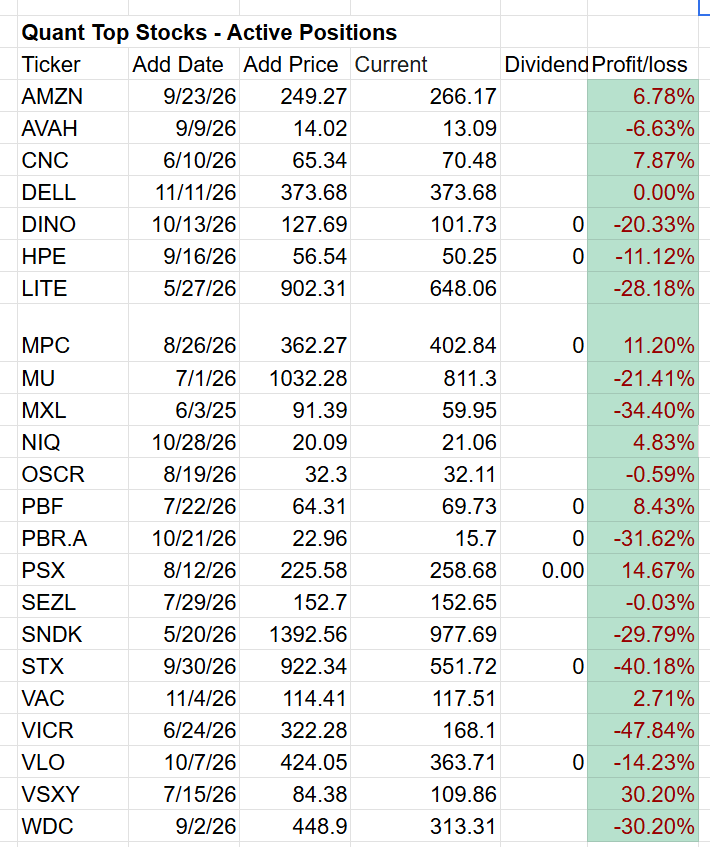
- Active Positions
- Quick Links
The momentum stocks in the portfolio as a group rallied a little since last week. Risk off still remains in control in the stock market, however.
Removing both Credo and Intel in this update. Both lost Momentum and EPS ranking in the Quant system and meet the criteria for Removal. They both were hit hard in the recent panic selloff of IT stocks.
Add: DELL (Dell)
REMOVE: CRDO (Credo Technology), INTC (Intel)
What does the company do?
Dell Technologies Inc. (NYSE: DELL) is a global technology company providing computers, servers, storage, networking equipment and IT services. Its two main divisions are Infrastructure Solutions Group (ISG), which supplies enterprise servers, storage and AI-optimized infrastructure, and Client Solutions Group (CSG), which offers desktops, laptops, workstations and accessories. Dell also provides IT consulting, support, financing and subscription-based technology services to businesses, governments, educational institutions and consumers. Founded in 1984, the company is headquartered in Round Rock, Texas.
Why Some Investors Are Bullish
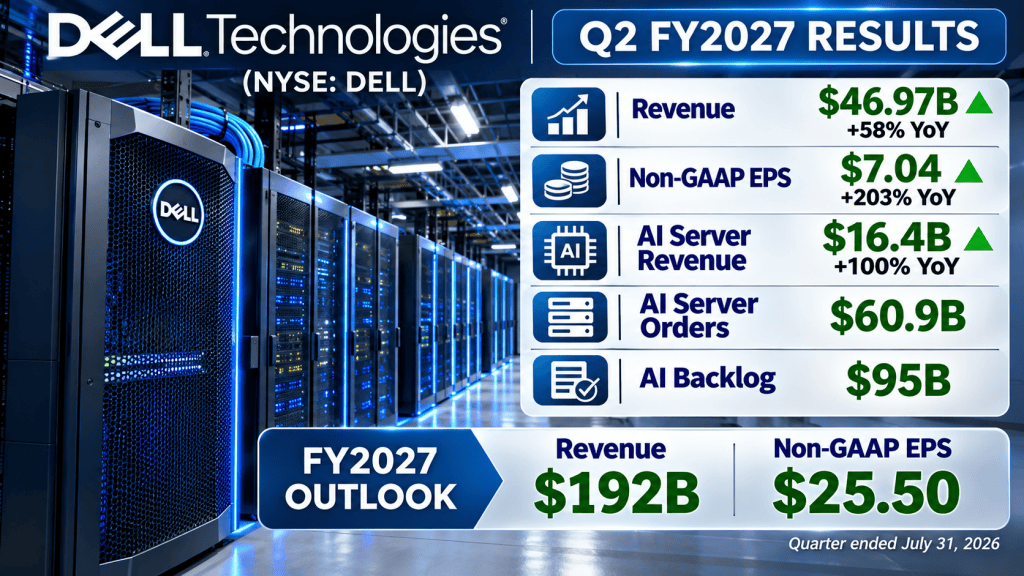
- Exceptional revenue growth. Revenue reached a record $46.97 billion, up 58% year over year, significantly exceeding the $29.78 billion reported in the prior-year quarter.
- Strong earnings growth. Non-GAAP EPS climbed 203% to $7.04, beating analyst expectations of approximately $4.91. Net income increased to $4.13 billion from $1.16 billion, while operating income surged 204%.
- Explosive AI server demand. Dell booked a record $60.9 billion in AI server orders, generated a record $16.4 billion in AI server revenue and ended the quarter with a record $95 billion backlog. This provides substantial visibility into future demand, although backlog conversion and delivery timing remain important.
- Broad-based business growth. Infrastructure Solutions Group revenue increased 89% to $31.8 billion, with operating income rising 225% to $4.8 billion. Traditional servers and networking grew 122%, storage increased 26%, and Client Solutions Group revenue advanced 20% to $15 billion. Growth is extending beyond AI servers into Dell’s broader product portfolio.
- Raised guidance and strong shareholder returns. Dell raised its fiscal 2027 revenue forecast to $192 billion and non-GAAP EPS guidance to $25.50. It also increased its AI-optimized server revenue outlook to $74 billion. Operating cash flow reached $2.23 billion for the quarter, and Dell returned a record $4.3 billion to shareholders through dividends and share repurchases.
What Bears Are Worried About
- Heavy dependence on AI spending. A significant portion of Dell’s growth now comes from AI servers and data-center infrastructure. Any slowdown in spending by major cloud providers or enterprise customers could negatively affect revenue, earnings and investor expectations.
- Hardware competition and margin pressure. Dell operates in a competitive, capital-intensive industry. AI servers require expensive components, including advanced processors and memory. Supply constraints, pricing pressure and changes in product mix could limit future margin expansion despite strong revenue growth.
- High expectations and execution risks. Dell’s ambitious growth outlook leaves little room for disappointment. The company must convert its substantial AI backlog into revenue while maintaining profitability and managing working capital. Any delays in customer spending, product deliveries or AI infrastructure projects could trigger a sharp stock-price reaction.
Why the Quants like this stock
P/E Non-GAAP (FWD) A- 12.9
PEG Non-GAAP (FWD) A 0.34
Revenue Growth (FWD) A- 34.23%
EPS FWD Long Term Growth (3-5Y CAGR) A- 38.42%
Return on Total Capital (TTM) A+ 30.88%
6M Price Performance A- 28.38%
FY1 Up Revisions (last 90 days) 25 Up 0 Down
Latest Quarter’s Earnings
Announce Date 9/1/2026
EPS GAAP Actual $6.34 (Beat by $1.94)
EPS Normalized Actual $7.04 (Beat by $2.12)
Revenue Actual $46.97B
Revenue Surprise Beat by $2.48B
My View
Dell is benefiting enormously from the AI infrastructure boom, with record orders, accelerating revenue and substantially higher earnings. Its growth is also broadening into traditional servers, storage, networking and commercial PCs. The $95 billion AI backlog and higher full-year guidance are particularly encouraging. Dell offers compelling exposure to the AI infrastructure market, but expectations are high, making execution and continued profitable growth essential.
Active Positions
Quick Links
- Live Scorecard
- Model Portfolio Quant Alpha’s II
- Click here for the Quant Alpha’s II details
- Model Portfolio Quant 30
- Click here for the Quant 30 details
- Model Portfolio Quant Dividend and Growth 25
- Model Portfolio Quant Top Stocks
- Click here for the Quant Top Stocks details
- Model Portfolio Quant Alpha’s – Legacy
- Click here for the Quant Alpha’s – Legacy details
- Position Trader educational blog posts
- Position Trader – blog post user guide
All content on this site is for informational purposes only and does not constitute financial advice. Consult relevant financial professionals in your country of residence to get personalized advice before you make any trading or investing decisions. This post was written with the assistance of artificial intelligence. The original ideas and final review are human-generated. Disclaimer
Copyright 2023-2026 SwingTrader.Trading. All Rights Reserved.

